ESG in Manufacturing
Closing the Gap Between Ambition and Decarbonisation
Reading Time
5 min
Article Sections
5
Share Links
3
On This Page
Article Section
Ambition Has Outpaced Infrastructure
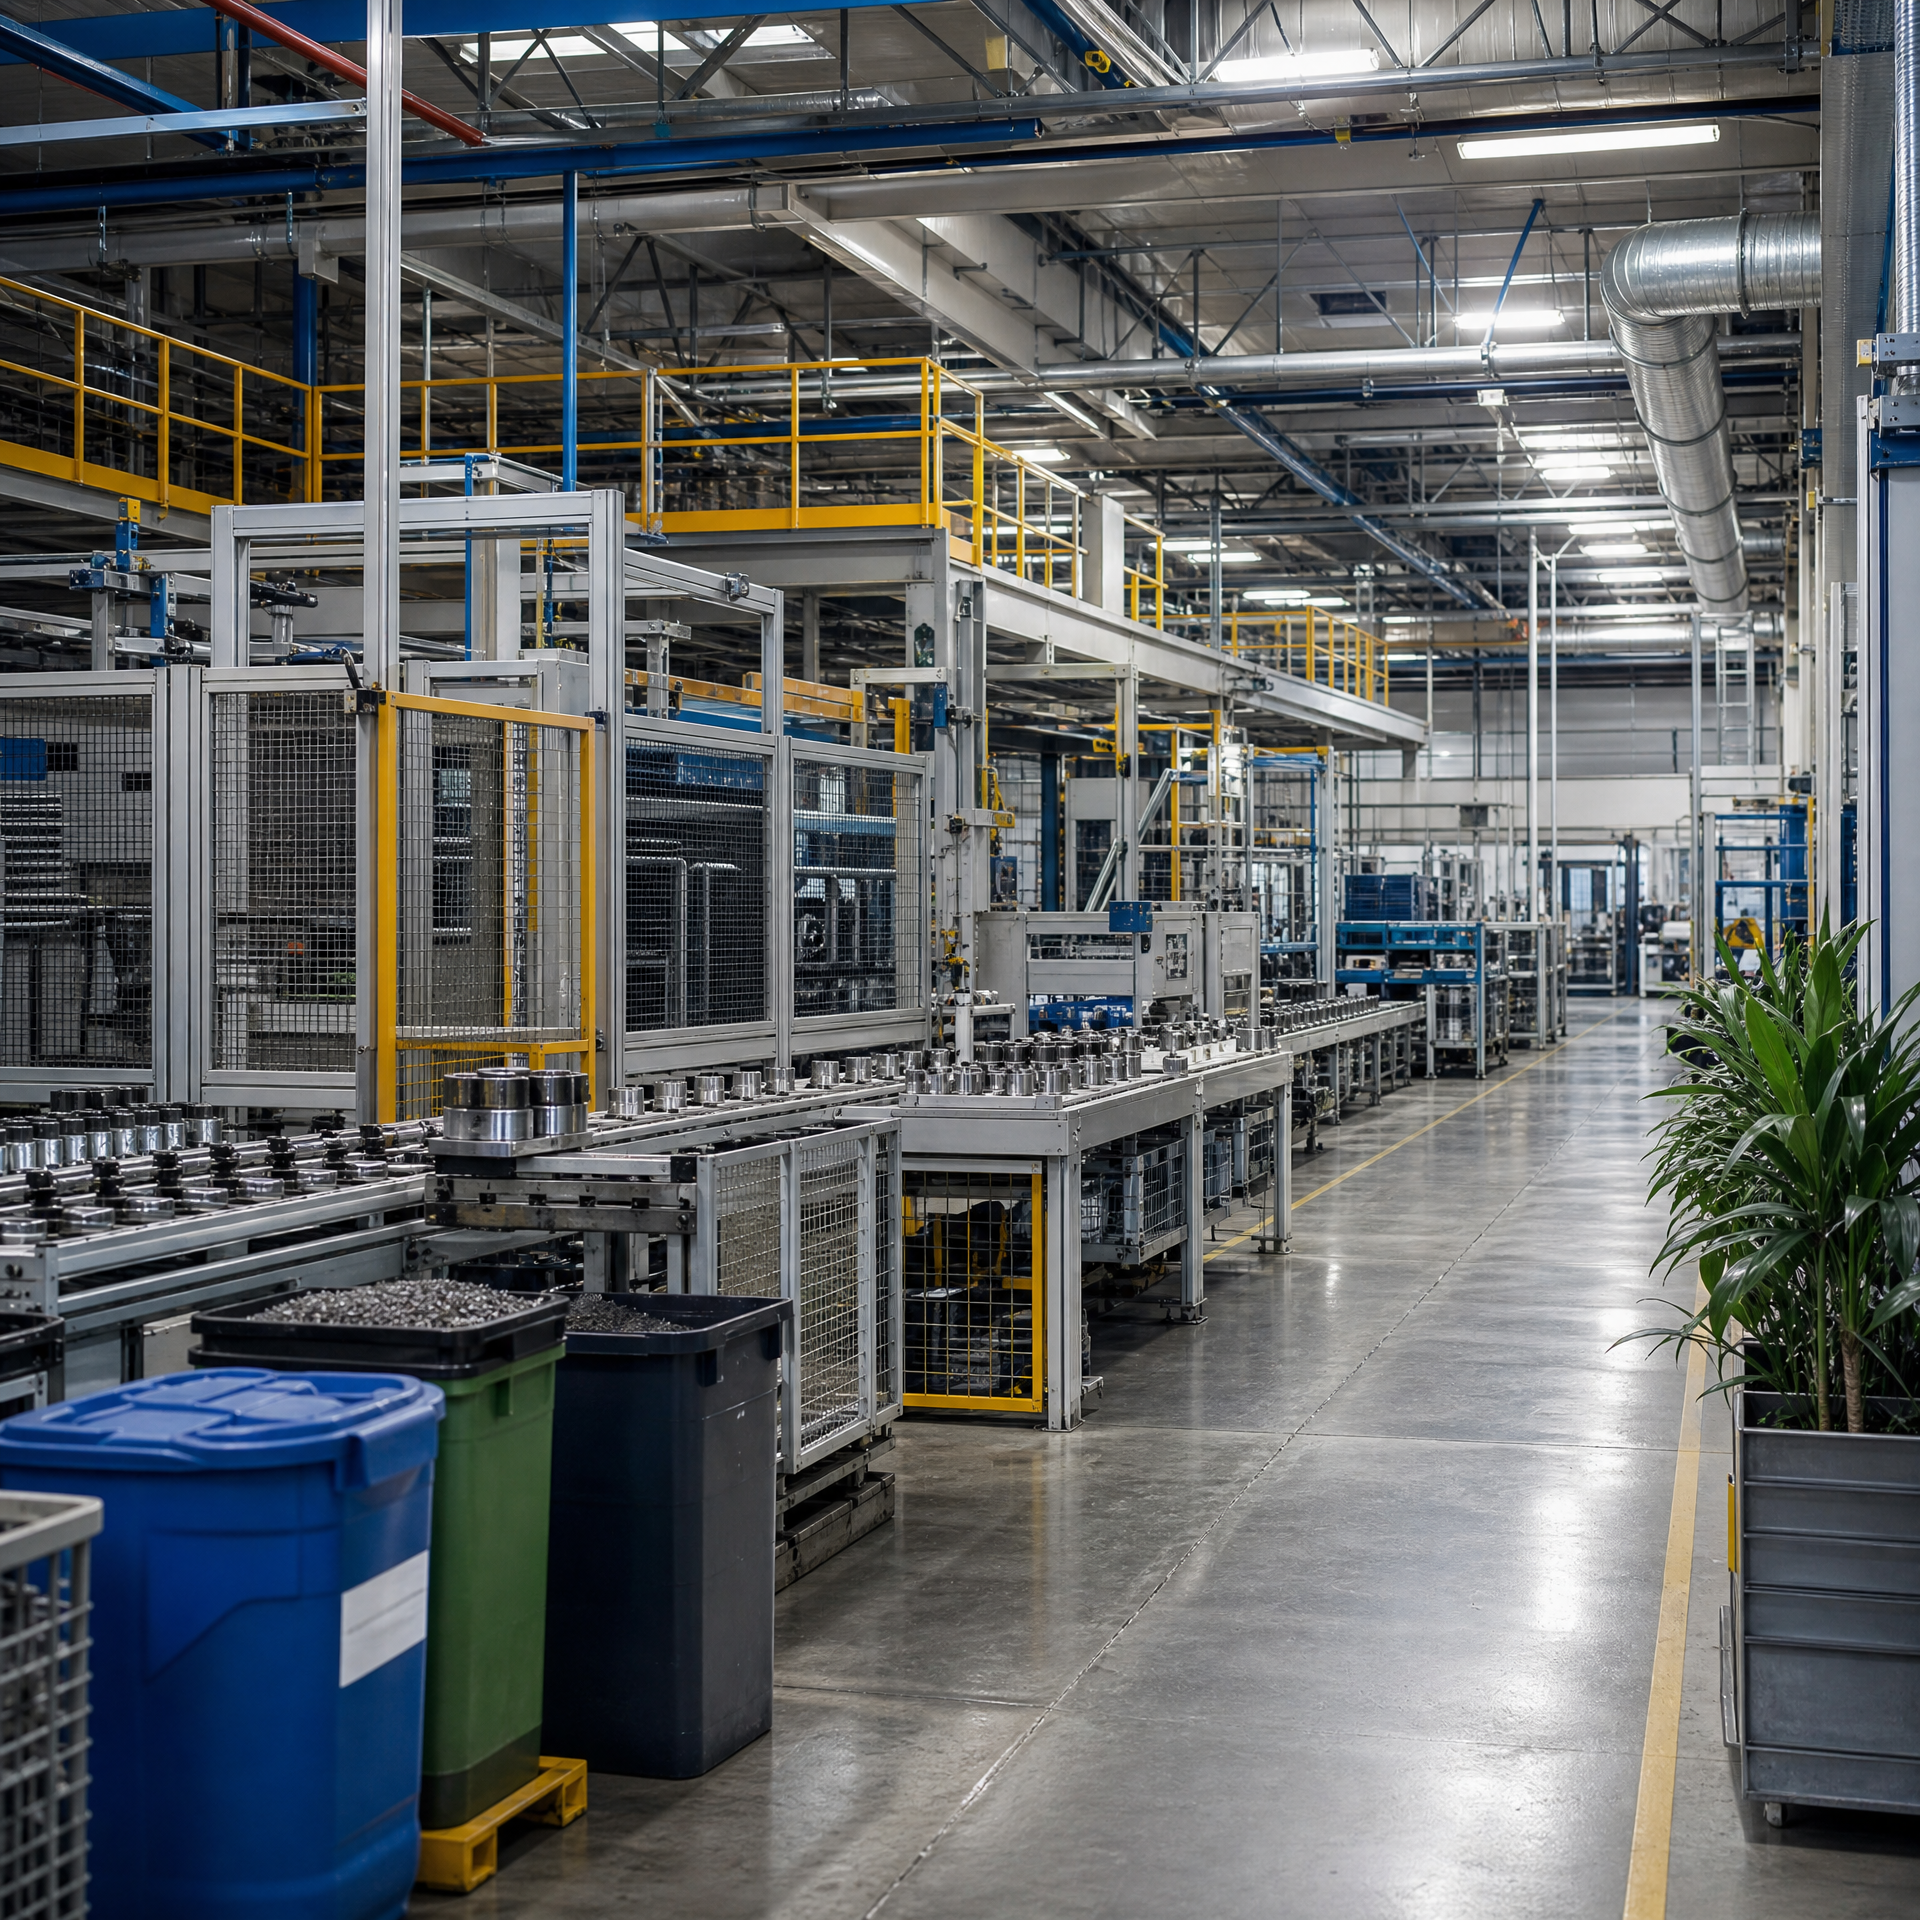
Manufacturing's environmental footprint is concentrated in Scope 1, 2, and 3 emissions, which together account for up to 90% of a manufacturer's carbon footprint, with the majority originating in the value chain rather than direct operations. Heavy industry carries a disproportionate share of this burden: the global steel sector alone emits 2.6 billion tonnes of CO2 annually, representing 7-9% of total global emissions, and hydrogen-based direct reduction, while capable of cutting sector emissions by up to 95%, requires a 15-20x increase in clean hydrogen production capacity that current infrastructure cannot support.
Energy management compounds the challenge, since energy is typically the single largest cost and environmental impact driver in manufacturing operations. Adoption of ISO 50001 energy management systems can deliver a 25-40% reduction in industrial energy consumption, but that reduction still depends on fuel switching from coal and oil to natural gas, electrification, and green hydrogen for high-temperature processes that most facilities have not yet made.
Regulation has moved faster than infrastructure. The EU CSRD now mandates comprehensive ESG reporting for roughly 50,000 companies using ESRS standards, the US SEC requires climate disclosures from publicly listed manufacturers, and India's SEBI BRSR framework applies to the country's top 1,000 listed companies, each running on a different timeline and data standard.
Article Section
Where the Gap Actually Bites?
The business case is proven, execution is not
Proactive ESG management is linked to 40-60% fewer environmental incidents, energy efficiency programs deliver 15-25% energy savings, and sustainably manufactured products command 5-20% price premiums in select markets. Manufacturers with robust ESG reputations also see 20-30% lower employee turnover, giving ESG integration a workforce stability dividend that goes beyond compliance. Yet these gains cluster among the largest, best-resourced manufacturers, while SMEs face disproportionate capital and resource barriers in meeting the same requirements, meaning the business case is real but unevenly accessible across the sector.
Regulatory fragmentation is raising, not lowering, the cost of compliance
Rather than converging, ESG regulation is multiplying. The EU's CSRD, CBAM, and CSDDD apply distinct thresholds and obligations from the US SEC's climate rules and California's Scope 3 mandates, while India's BRSR and Asia-Pacific's ISSB-aligned standards add further variation. Manufacturers operating across these jurisdictions face a genuine patchwork, and the lack of harmonization increases compliance costs and complicates cross-border operations, even as GRI, ISSB, and BRSR frameworks move toward closer alignment.
The Scope 3 data problem undermines credible disclosure
Since Scope 3 emissions typically represent the majority of a manufacturer's footprint, incomplete data at that level compromises the credibility of the entire disclosure. Scope 3 data is often incomplete or estimated, particularly across multi-tiered supply chains, and social metrics such as labour conditions are similarly difficult to quantify and verify. As regulators tighten expectations around assurance, and the EU Green Claims Directive and US FTC Green Guides target unsubstantiated claims, manufacturers reporting on unverified estimates carry growing legal and reputational exposure.
Article Section
What Leaders Should Do Now?
Prioritise Scope 3 data infrastructure before expanding targets
Leaders should treat standardised data collection and supplier engagement as a prerequisite for credible target-setting, since a science-based target built on estimated Scope 3 data invites the same scrutiny regulators are now applying to unsubstantiated claims.
Sequence decarbonisation investment around what technology can currently deliver
Given that green hydrogen capacity remains far short of what heavy industry decarbonisation requires, manufacturers should prioritise proven efficiency levers, such as ISO 50001 adoption and electrification, while treating hydrogen-dependent pathways as a longer-term bet rather than a near-term compliance plan.
Build a core, framework-agnostic ESG metric set
Rather than building separate reporting processes for CSRD, SEC, and BRSR, manufacturers should establish a single source of ESG data mapped to multiple frameworks, reducing the compounding cost of regulatory fragmentation and improving audit readiness as assurance requirements tighten.
Article Section
Conclusion
Manufacturing has largely settled the question of whether ESG integration pays off. The data on cost savings, pricing premiums, and capital access is consistent across the sector. What remains unresolved is whether the industrial base, data infrastructure, and regulatory landscape can move at the pace that ambition now demands.
The manufacturers that close that gap, by building credible data foundations and sequencing investment around what current technology can actually deliver, will be the ones setting the pace for the rest of the sector as decarbonisation timelines tighten.
Article Section
Frequently Asked Questions
How much of global greenhouse gas emissions does manufacturing account for?
Manufacturing accounts for approximately 20% of global greenhouse gas emissions.
Why is decarbonising the steel industry so difficult?
Steel emits 2.6 billion tonnes of CO2 annually, and hydrogen-based direct reduction, the primary decarbonisation pathway, requires a 15-20x increase in global clean hydrogen production capacity that does not yet exist.
Does ESG performance translate into measurable financial benefits for manufacturers?
Yes, ESG leaders see 40-60% fewer environmental incidents, 5-20% pricing premiums, and 20-30% lower employee turnover compared with laggards.
Why is Scope 3 emissions data a particular challenge for manufacturers?
Scope 3 emissions can account for the majority of a manufacturer's footprint, yet the data is often incomplete or estimated across multi-tiered supply chains, undermining the credibility of disclosures built on it.
Why are manufacturers facing rising compliance costs despite regulatory convergence efforts?
Manufacturers must navigate distinct requirements across the EU CSRD and CBAM, the US SEC climate rules, India's BRSR, and ISSB-aligned standards in Asia-Pacific, and this lack of harmonization increases compliance costs even as frameworks move toward closer alignment.
Keep Reading
Related Blogs
All Industries
What CSRD Actually Means for Indian Companies Supplying Europe
Understanding the value chain impact of CSRD.
Read more
All Industries
India's Green Credit Programme vs Carbon Credits
Are They the Same Thing? No. Here's Why
Read more
All Industries
Decarbonisation Roadmaps That Actually Work
What the Best Indian Companies Do Differently
Read moreNext Step
Ready to turn ESG complexity into strategic advantage?
Talk to ESG Astraa about disclosures, climate strategy, governance controls, and execution support for your team.