ESG in the Global Energy and Power Sector
Managing the Transition Under Pressure
Reading Time
5 min
Article Sections
5
Share Links
3
On This Page
Article Section
A Sector Splitting by Sub-Sector, Not Just by Company
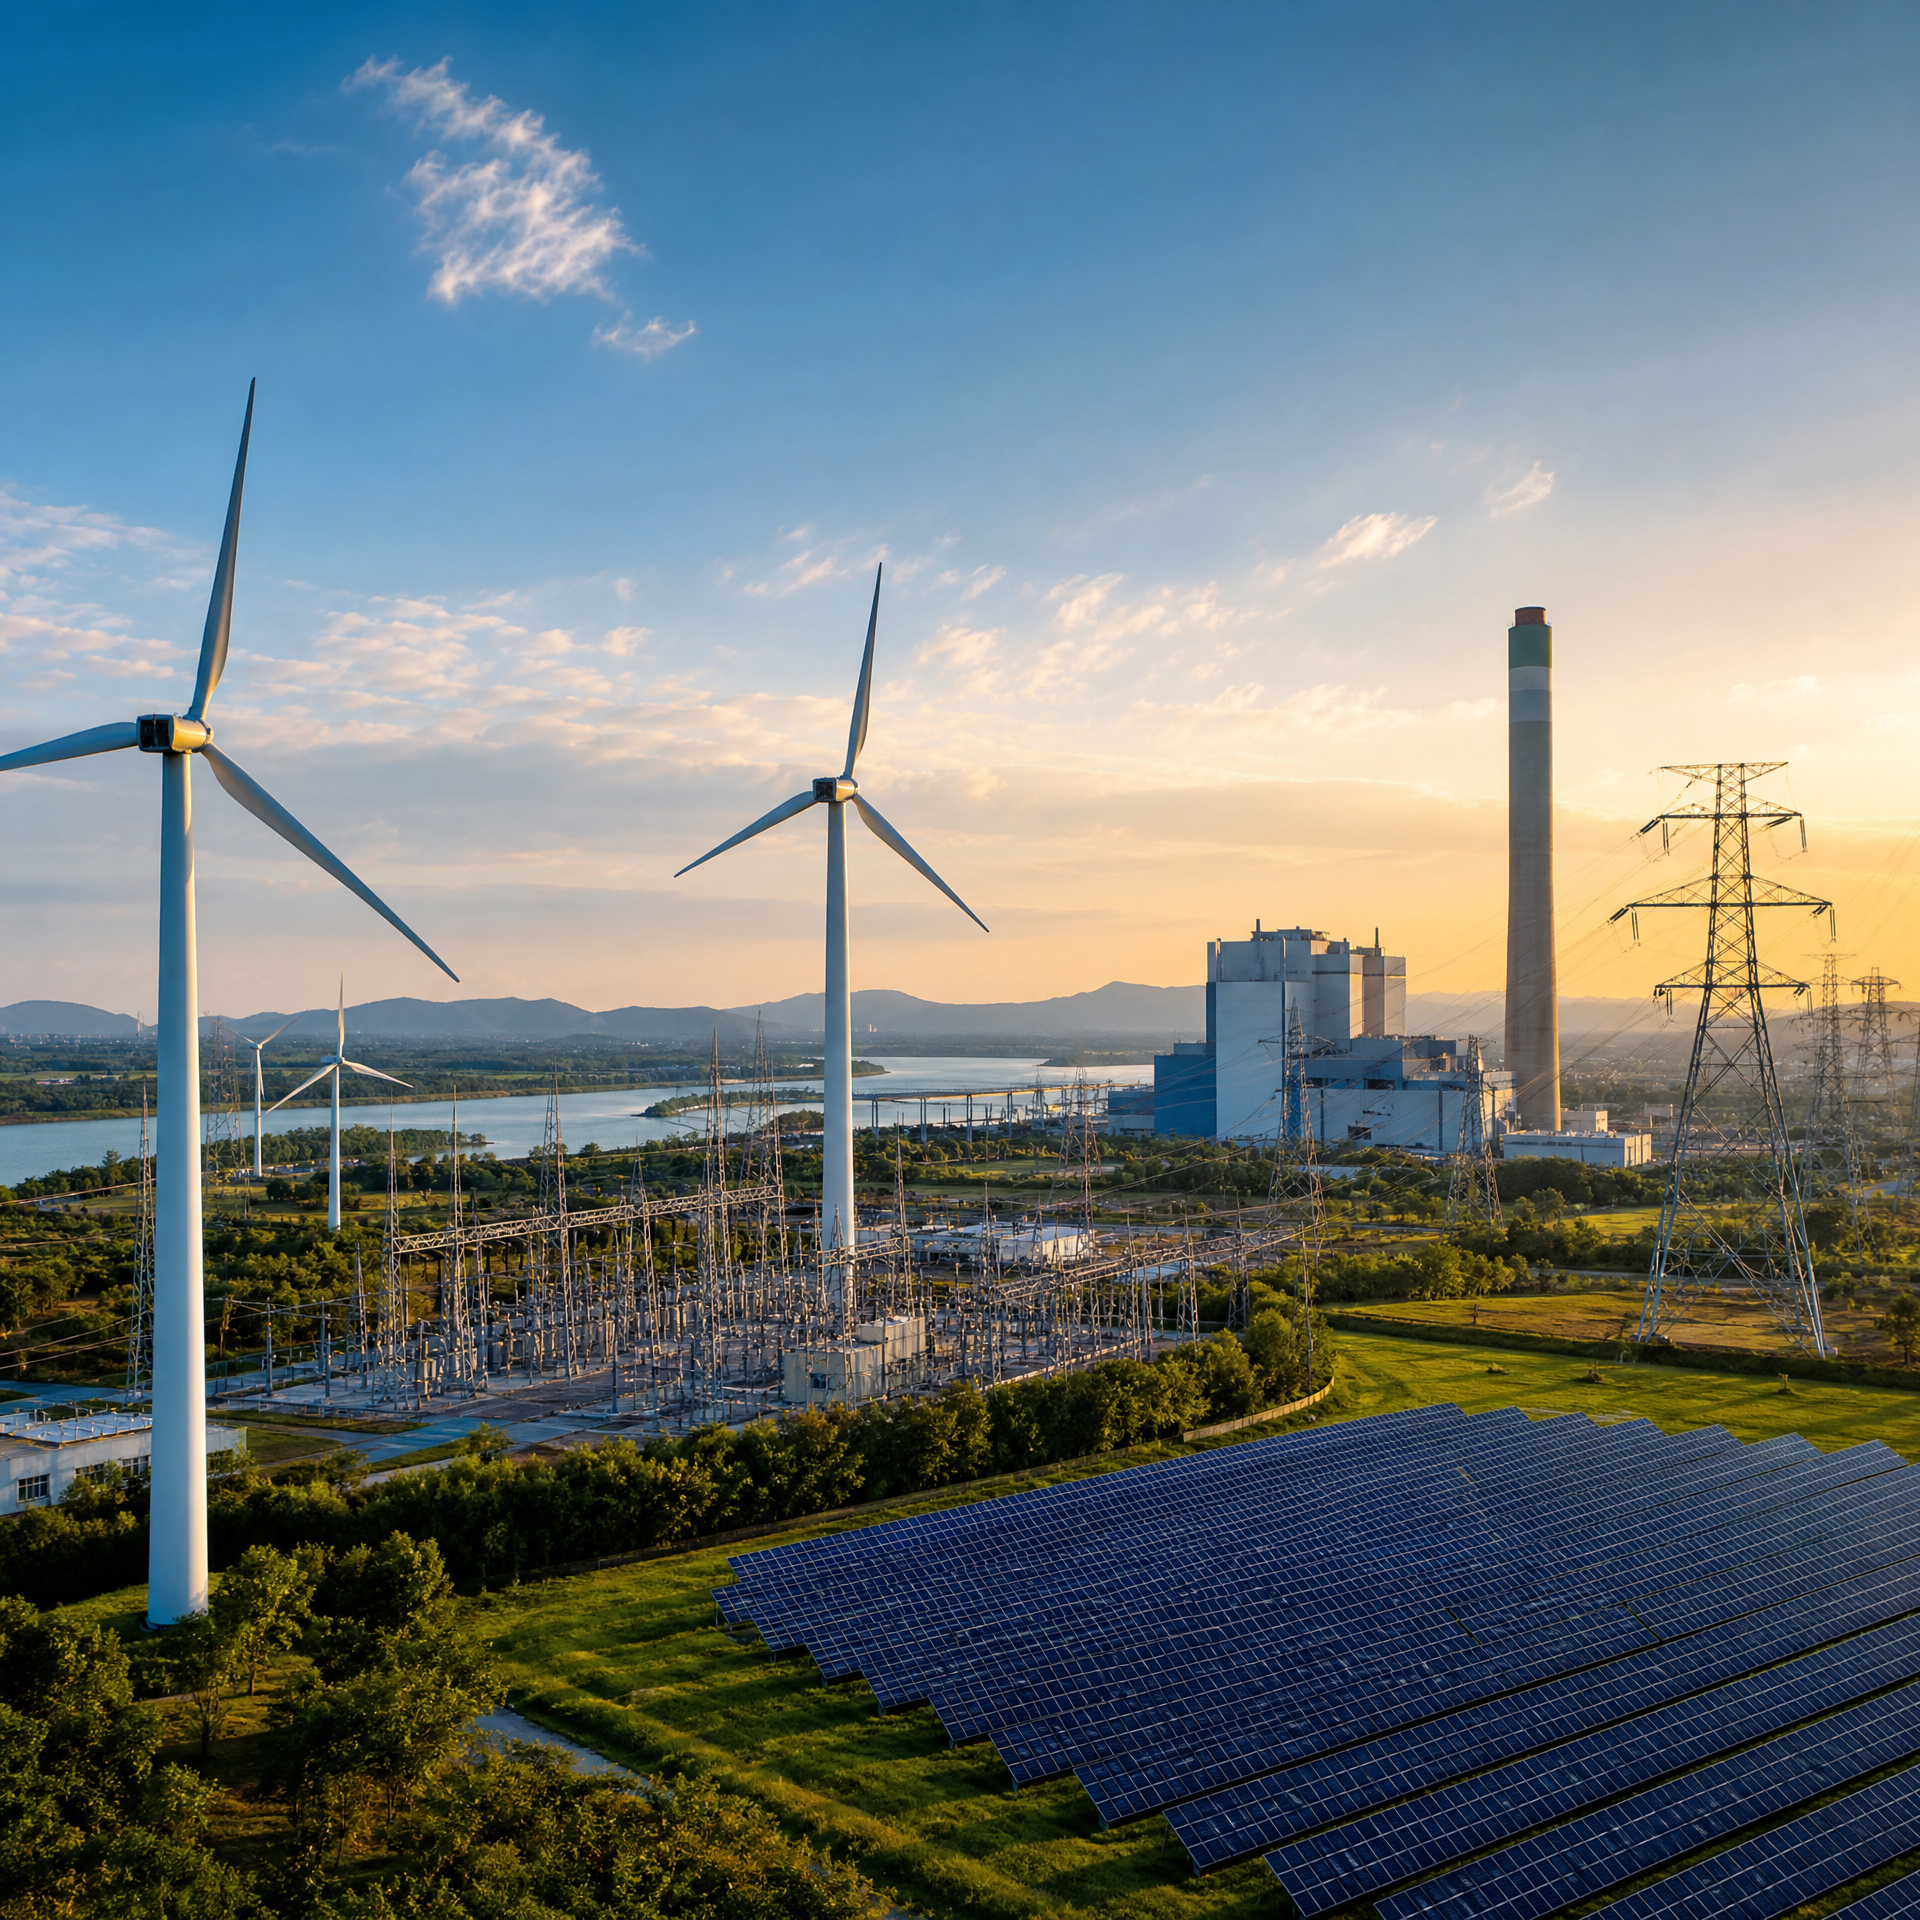
ESG maturity across the energy sector is no longer uniform, and the gap is widening by sub-sector rather than by company size. Integrated oil majors such as TotalEnergies, Shell, BP, and Equinor have reached advanced environmental and governance maturity, with board-level ESG oversight and capital increasingly reallocated toward low-carbon assets. Renewable energy companies, exemplified by Orsted's complete exit from fossil fuels, have become the industry's ESG benchmark on every pillar. National oil companies remain furthest behind, constrained by sovereign mandates and hydrocarbon-dependent state revenues, with Scope 3 emissions largely unaddressed.
What ties these tiers together is where the capital is actually going. European majors are directing between 25% and 50% of capital expenditure toward renewables and low-carbon assets. Green bonds, where the energy sector accounts for 41% of global issuance, and transition finance instruments tied to sustainability-linked loans, are underwriting the shift. Meanwhile the assurance infrastructure meant to verify all of this remains thin: only 45% of S&P 500 energy companies carry any independent assurance on their ESG data, and most of that sits at the limited rather than reasonable level regulators are moving toward. The commitments are getting bigger. The verification behind them is not keeping pace.
Article Section
Two Bets on Two Different Halves of the Problem
The renewables bet
European majors are converting balance sheets, not just strategy decks. TotalEnergies has scaled its renewable portfolio to 22 gigawatts installed and contracted, targeting 100 gigawatts by 2030, and allocated a third of its 2025 capital budget to low-carbon electricity. BP has set a parallel 50-gigawatt target. The risk sits in operations rather than finance: renewable assets reward offshore engineering, grid management, and power trading capabilities that oil majors are still building, and acquiring generation capacity without that expertise tends to destroy value rather than create it.
The molecule bet
ExxonMobil and Chevron have taken the opposite route, prioritising carbon capture and blue or green hydrogen over direct power generation, a choice that plays to subsurface geology and large-scale project execution rather than asking an oil major to compete with utilities. The gap this bet has to close is steep. Global CCUS capacity reached 50 million tonnes of CO2 per year in 2024, while the IEA's net zero scenario requires 1.2 billion tonnes by 2030, a 24-fold scale-up funded partly by the 45Q credit's $85 per tonne incentive. Over 300 projects are in the pipeline, each requiring $500 million to $2 billion and five to seven years to build.
The shared blind spot
Both strategies are, at their core, operational plays. They target Scope 1 and 2 emissions, direct operations and purchased energy, which together account for under 15% of total lifecycle emissions at an oil and gas company. Scope 3, generated when customers burn the products these companies sell, makes up 80-95% of the total, and neither strategy sets a direct target for it. Portfolio diversification reduces exposure to that share over time, but exposure management is not the same commitment as reduction, and the distinction is becoming harder for investors to ignore. Capital markets are already pricing credible execution over strategic category. Pioneer's disciplined operational program, with no renewables pivot at all, still earned a premium $59.5 billion acquisition by ExxonMobil. Orsted's full pivot to offshore wind grew its market value more than fivefold before recent volatility exposed the risk of concentrating a transition in a single technology.
Article Section
What Leaders Should Do Now?
Match the bet to the balance sheet's actual strengths
Companies with pipeline networks, geological expertise, and large-project management are structurally better positioned for CCUS and hydrogen than for competing with utilities on power generation, and vice versa. Leadership teams should audit core capabilities before capital, not after.
Treat Scope 3 disclosure as a credibility test, not a target-setting exercise
With independent assurance still covering under half of S&P 500 energy companies, publishing directionally honest Scope 3 estimates now, even without full reduction targets, builds more investor trust than silence does, and it is measurably cheaper than repairing credibility after a greenwashing claim.
Build assurance-grade data before regulators require it
CSRD and ISSB are moving toward reasonable assurance, equivalent to financial audit scrutiny. Digital ESG data platforms and automated audit trails are the infrastructure that makes that transition possible, and the companies building it now will not be scrambling when the mandate lands.
Article Section
Conclusion
The energy sector's net zero race is not one contest with two paces. It is two different bets on two different halves of the emissions problem, and both currently stop short of the 80-95% of emissions that Scope 3 represents.
The companies that win the next decade will not be the ones who chose the more fashionable bet. They will be the ones who could show, with assurance-grade evidence, exactly what their bet did and did not solve.
Article Section
Frequently Asked Questions
What is the core difference between European and US energy majors' net zero strategies?
European majors like TotalEnergies and BP are reallocating capital directly into renewable generation, while US majors like ExxonMobil and Chevron are investing in carbon capture and hydrogen instead.
Why does Scope 3 matter so much for oil and gas companies?
Scope 3 emissions, generated when customers use the products a company sells, account for 80-95% of total lifecycle emissions in oil and gas, dwarfing direct operational emissions.
Is carbon capture technology ready to scale at the pace net zero requires?
Not yet: global CCUS capacity reached 50 million tonnes of CO2 per year in 2024, far short of the 1.2 billion tonnes the IEA's net zero scenario requires by 2030.
Does a renewables pivot outperform an operational efficiency strategy in the market?
Not necessarily: Pioneer earned a premium acquisition price through operational discipline alone, while Orsted's full renewables pivot delivered strong but more volatile returns, suggesting markets reward credible execution over strategic category.
What should energy company leaders prioritise before setting their own transition strategy?
An honest audit of existing operational capabilities, since misaligned bets, such as acquiring renewable assets without power-sector expertise, tend to destroy rather than create value.
Keep Reading
Related Blogs
Energy & Power
Structuring a Renewable Power Purchase Agreement in India
What Businesses Need to Know?
Read more
Energy & Power
India's Carbon Credit Trading Scheme Has Launched
What Every Listed Company Must Do Now?
Read more
Energy & Power
What Is a "Just Transition" ?
Why Is It Reshaping Global Energy Policy?
Read moreNext Step
Ready to turn ESG complexity into strategic advantage?
Talk to ESG Astraa about disclosures, climate strategy, governance controls, and execution support for your team.